5 Steps to Lower Your Insurance Bill and Save Hundreds (Easy Guide for Minnesotans)
Insurance · October 9, 2026 · 6 min read
Have you opened your latest insurance renewal and felt a bit of a “sticker shock”? You aren’t alone. Lately, it feels like everything in the grocery store and at the gas pump has a higher price tag, and unfortunately, insurance hasn’t been the exception. In fact, here in Minnesota, we recently saw a staggering 34% jump in home insurance rates: the highest increase in the entire country.
I’m Christopher Griepp, and as a local agent here in Mendota Heights, I’ve had many conversations across kitchen tables and office desks about this very topic. It’s tough to see those numbers climb, especially when you’re doing everything right to protect your family. But while we can’t control the wild Minnesota weather (as much as we’d like to stop the hail!), we can take control of how we structure your protection.
The good news is that you don’t have to just “take it” when it comes to rising premiums. There are several practical, straightforward ways to lower your bill without leaving yourself vulnerable. Here is my five-step guide to finding those savings and getting your budget back on track.
1. The Power of the “Bundle” (Home + Auto)
If you have your car with one company and your house with another, you are likely leaving hundreds of dollars on the table. In the insurance world, loyalty and consolidation are rewarded. By placing both your Auto Insurance and your Home Insurance under one roof, you can often unlock multi-policy discounts.
Think of it like a “buy more, save more” deal at your favorite local shop. When I bundle these policies for my clients, I often see savings that can reach into the hundreds of dollars every year. It’s not just about the discount, though. Having one point of contact means you don’t have to remember which agent handles which “what-if.” Whether it’s a fender-bender on I-494 or a tree limb falling on your garage after a summer storm, you just call me.
Beyond the savings, bundling simplifies your life. You have one renewal date to remember and one person who truly understands your entire financial picture. It’s the easiest first step to lowering that monthly bill.
2. Modernize Your Protection with Impact-Resistant Shingles
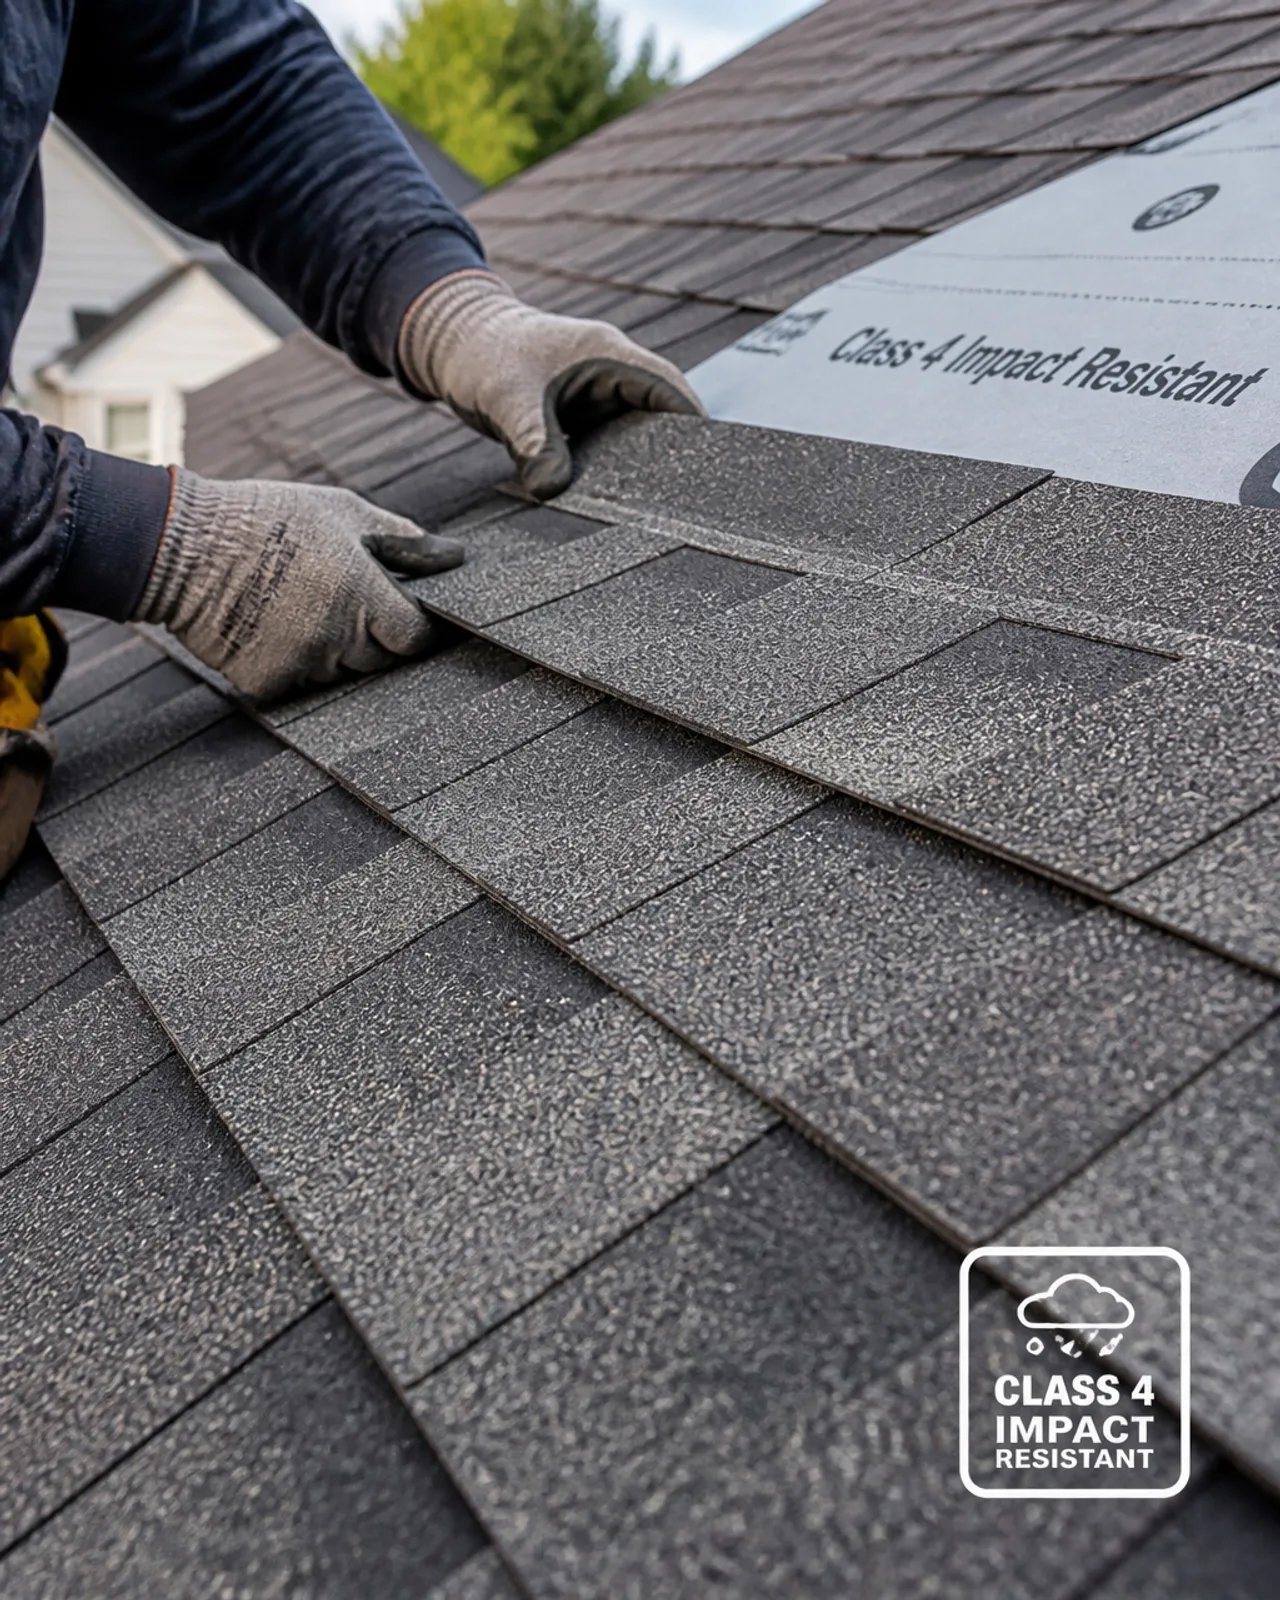
We all know the sound. That low rumble of a June thunderstorm that suddenly turns into the “tink-tink-tink” of hail hitting the windows. In Minnesota, hail isn’t a matter of if, it’s a matter of when. Because hail damage is one of the primary reasons for that 34% rate jump in our state, insurance companies are looking for ways to reward homeowners who take proactive steps.
If you’re planning on replacing your roof soon, or if you’ve recently done so, ask your contractor about Class 3 or Class 4 impact-resistant shingles. These aren’t your average shingles; they are designed to withstand the force of hail without cracking or losing their protective granules.
Why does this help your bill? Because a tougher roof means you are much less likely to file a claim after a storm. I offer specific discounts for these high-performance materials. It’s a win-win: you get a roof that lasts longer and protects your pots and pans better, and I get to lower your premium because your home is now a lower risk. It’s one of the most effective ways to hail-proof your budget.
3. Leverage Tech-Savvy Savings (The Signal App)
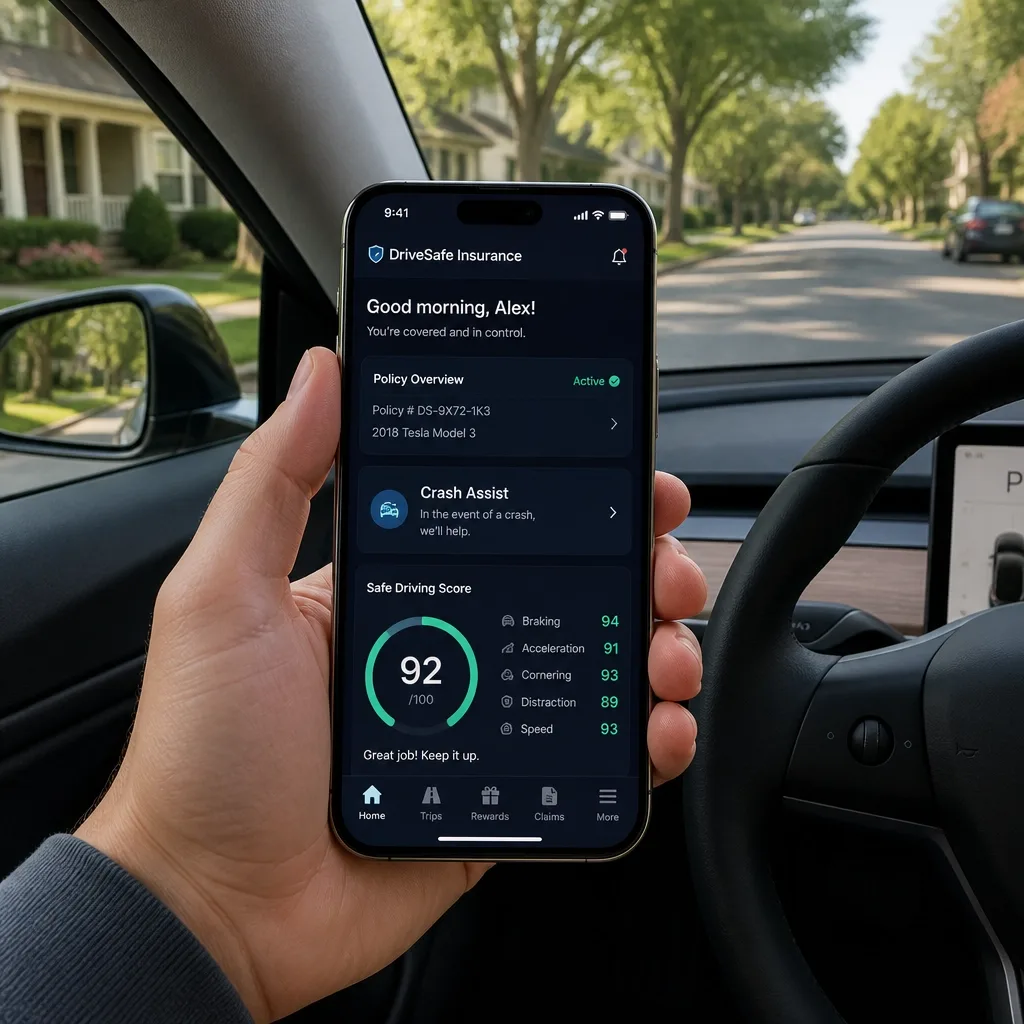
We use apps for everything these days: ordering coffee, tracking our steps, and even checking the lake levels. So why not use an app to lower your insurance bill?
I encourage many of my clients to use the Signal app. It’s a simple tool that sits on your phone and rewards you for the safe driving habits you already have. By avoiding things like hard braking and distracted driving (we all know we shouldn’t be texting at the red light!), you can earn a discount on your auto policy.
But the Signal app isn’t just about the discount; it’s about your family’s safety. It features something called Crash Assist, which can detect if you’ve been in a serious accident and help connect you with emergency services or a locksmith service if you’re stranded. It’s like having a digital co-pilot that pays you to be careful. If you’re already a safe driver, you might as well get the credit (and the lower premium) for it.
4. Schedule a “Friendly Review”
When was the last time you actually talked to someone about your insurance? Not just a chatbot or a 1-800 number, but a real conversation? Life changes fast. Maybe you finished your basement, bought a new engagement ring, or finally started that small business out of your garage. If your insurance policy is three years old, it might be protecting a version of your life that doesn’t exist anymore.
I offer a service called the Friendly Review. This isn’t a high-pressure sales pitch. It’s a neighborly conversation where we sit down, either in my Mendota Heights office or over the phone, and look at your current coverage.
During these reviews, we often find hidden savings. For example, you might be paying for coverage you no longer need, or you might be eligible for a new discount you didn’t qualify for last year. On the flip side, we might find a gap where you’re under-insured, which could save you thousands in the long run if a disaster hits. It’s all about finding the right balance between affordability and protection.
5. Adjust Your Deductibles and Right-Size Your Coverage
The final step is looking at the fine print of your policy. Your deductible is the amount you pay out of pocket before your insurance kicks in. Many people have a $500 deductible because that’s what was standard twenty years ago. However, by raising your deductible to $750 or $1,000, you can often see a noticeable drop in your monthly premium.
Think of it this way: insurance is meant to protect you from the big stuff: the house fire, the major car accident, the total loss. By taking on a little more of the small stuff risk yourself, you lower the cost of the overall policy.
Additionally, we can look at right-sizing your coverage levels. Are you over-insured on an older vehicle? Do you have the right amount of Life Insurance to protect your children’s future, or are you paying for a policy that doesn’t fit your current goals? We’ll look at everything from your umbrella coverage to your condo policy to ensure you aren’t paying for fluff but are fully protected where it counts.
Let’s Have a Conversation
I know that insurance can feel complex and sometimes frustrating, especially when rates are rising. But you don’t have to navigate it alone. I live and work right here in the community, and my goal is to make you smarter about your insurance options so you can make the best decision for your family.
Whether you’re in Mendota Heights, elsewhere in Minnesota, or even in the other states where I’m licensed (CO, AZ, MI, and WI), I’m here to help. Let’s look at your policies together and see how much we can save you.
Give me a call or stop by the office. Let’s get that insurance bill moving in the right direction (down).
Christopher Griepp
Christopher Griepp is a Marine Corps veteran and licensed insurance agent with 18 years of experience. Based in Mendota Heights, MN, he helps families and businesses across five states find coverage that actually makes sense — no jargon, no pressure, just honest advice.